
Neo-Banking & Cross-Border Money Transfer Project | WeInvesta
Digital financial services are changing how people and businesses manage money. Customers use mobile applications to make payments, freelancers receive international earnings, and businesses transfer money across borders.
These services depend on secure technology, reliable payment networks, financial partners, and regulatory compliance.
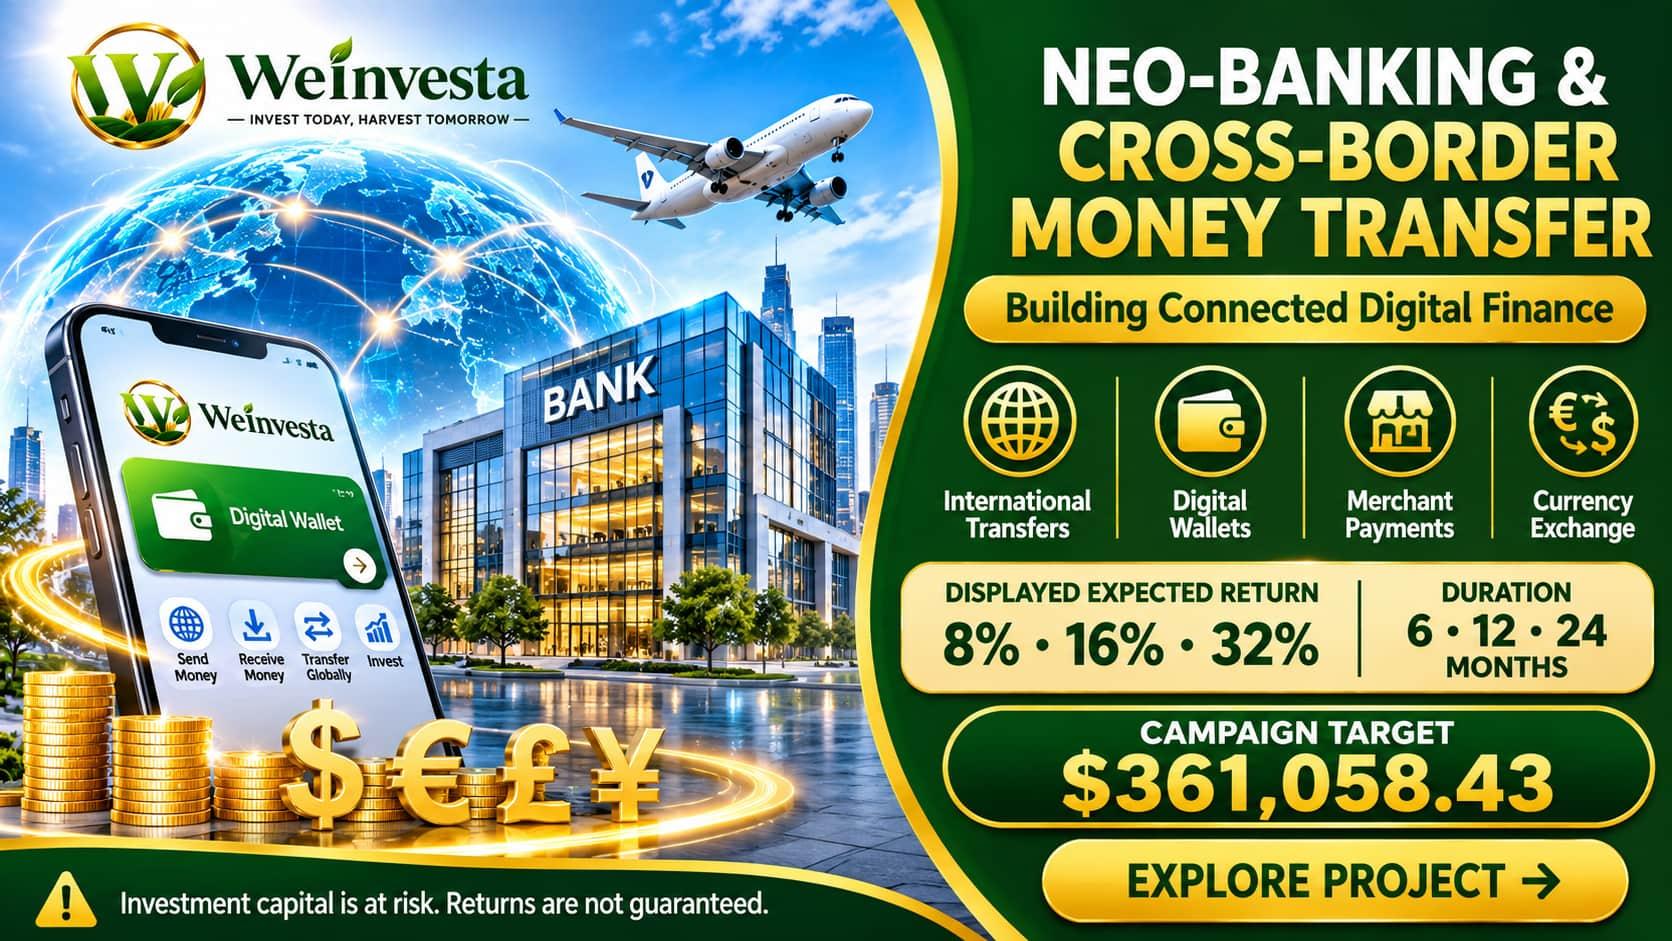
WeInvesta’s Neo-Banking & Cross-Border Money Transfer Platform is a proposed digital financial platform designed to support international money transfers, currency exchange, merchant payments, multi-currency accounts, and business transactions.
The project aims to develop a connected financial ecosystem for non-resident customers, freelancers, travelers, medical tourists, merchants, and people who regularly make international payments.
Before considering an investment, it is important to understand the platform's planned services, development stages, revenue model, and regulatory requirements.
Explore Project Details →
What Does the Platform Plan to Offer?
The proposed platform combines several digital financial services in one ecosystem.
1. International Money Transfers and Remittances
The platform plans to support cross-border money transfers for individuals and businesses.
Its intended services include remittance corridors, international transfers, and business payment solutions. The platform aims to make international transactions more accessible through digital channels.
The availability of these services will depend on payment partners, regulatory permissions, supported countries, and operational arrangements.
2. Multi-Currency Accounts and Digital Wallets
The project describes plans for multi-currency financial tools and digital wallets.
These features are intended to help users manage different currencies and access digital financial services through a mobile platform.
Digital wallets and business exchange tools may also support customer retention and recurring platform usage.
3. Merchant Payments and Business Settlements
The platform plans to support merchant payment gateways and cross-border business transactions.
Potential services include merchant payments, business settlements, and digital payment processing. These services are intended to help businesses manage transactions involving customers and partners in different markets.
4. Currency Exchange Services
Foreign exchange is another important part of the proposed business model.
The platform plans to facilitate currency exchange and generate revenue through exchange-rate spreads, subject to the applicable regulations and transaction arrangements.
A Two-Phase Development Strategy
The project describes a phased approach to developing its digital financial infrastructure.
Phase 1: Launch Through a Licensed Partner
The first phase aims to enter the market through a licensed financial partner rather than immediately obtaining independent licensing.
The planned development activities include:
Building the mobile application.
Integrating Know Your Customer (KYC) procedures.
Establishing Anti-Money Laundering (AML) monitoring.
Arranging card-issuing services through partners.
Integrating remittance and international payment networks.
Establishing a customer support centre.
Developing compliance monitoring systems.
This approach is intended to support an earlier market entry while operating under a partner's licensing framework.
Actual service availability will depend on the partner agreement, regulatory approval, technical integration, and compliance requirements.
Phase 2: Independent Licensing and Expansion
The second phase aims to pursue independent licensing after the platform achieves customer traction and develops sufficient compliance maturity.
The planned activities include:
Applying for the relevant independent financial licences.
Meeting applicable regulatory capital requirements.
Developing treasury management systems.
Establishing controls for microfinance products.
Expanding the wider digital banking infrastructure.
Progression to this phase will depend on regulatory approval, funding, operational readiness, and compliance requirements.
How Does the Project Plan to Generate Revenue?
The proposed commercial strategy includes several potential revenue sources.
Remittance Fees: Fees charged for processing international money transfers.
Foreign Exchange Spreads: Revenue opportunities from currency conversion and exchange-rate differences.
Debit Card Interchange: Potential income associated with eligible debit card transactions.
ATM Fees: Charges associated with applicable ATM services.
Merchant Settlement: Fees for processing and settling merchant payments.
Digital Wallet Services: Potential revenue from wallet-related financial services.
Freelancer Payouts: Charges for processing international payments to freelancers and remote workers.
Compliant Micro-Loan Interest: Potential revenue from interest earned on micro-loan products, subject to applicable licensing and regulatory requirements.
The project aims to build a diversified revenue model through payment processing, money exchange, remittances, and financial services.
Additional Feature: Emergency Micro-Loans for Active Investors
The project description includes a proposed emergency micro-loan facility for active investors.
Under the stated arrangement, eligible investors may be able to access emergency micro-loans of up to 80% of their invested principal, while their investment capital remains locked.
However, access is subject to credit checks and compliance requirements.
This facility should not be treated as guaranteed financing, automatic access to invested funds, or a withdrawal facility. Investors should review the applicable loan conditions, eligibility rules, charges, repayment obligations, and regulatory requirements before relying on this feature.
Key Investment Highlights
The project highlights several features of its proposed financial platform:
Digital banking and payment infrastructure.
International remittance and cross-border payment services.
Multi-currency account and digital wallet features.
Merchant payment gateways and business settlements.
Potential transaction-margin revenue from exchange and remittance services.
A cloud-native architecture designed for scalability.
A phased approach to financial licensing and market development.
Potential customer retention through digital wallets and business exchange tools.
These are planned capabilities and commercial objectives. Their success will depend on implementation, customer adoption, partnerships, regulatory approval, and market conditions.
Project Overview
Project InformationDetailsProject NameNeo-Banking & Cross-Border Money Transfer PlatformCategoryFintech & PaymentsMarketGlobal (Digital)StatusActiveDisplayed Expected Return32%Displayed Duration24 MonthsCampaign Target Amount$361,058.43Raised So Far$0.00Total Investors0Funding Progress0%Main Lock Period2 YearsEstimated Total Project RequirementUS$10.50M–US$14.50M
Displayed Investment Plans
The project page currently presents three selectable investment options:
Lock PeriodDisplayed Fixed RateInvestment RangePayout6 Months8%$100–$1,000,000At maturity12 Months16%$100–$1,000,000At maturity24 Months32%$100–$1,000,000At maturity
According to the displayed plans, the instant bonus is 0%, and payouts are scheduled at maturity.
Important Investment Terms: The general investment terms separately state a minimum investment of $1,000, a 24-month lock-in period, and a target of 20% total profit. These figures differ from the investment-plan cards, which show a $100 minimum, three available periods, and displayed rates of 8%, 16%, and 32%.
The displayed figures should not be assumed to have identical contractual conditions. Before investing, review the latest official project documents and confirm the applicable minimum investment, profit calculation, lock period, and payout terms.
Project Documents and Transparency
WeInvesta provides project-related documents for prospective investors to review.
The listed documents include:
WeInvesta Whitepaper
Sector-by-Sector Projects Profile
Business Plan
Investment Prospectus & Risk Overview
Risk Disclosure
Reviewing these documents can help investors understand the proposed business model, project development stages, investment structure, and associated risks.
Risks and Important Considerations
Digital banking and cross-border payment businesses operate in a highly regulated and technology-dependent environment.
The project identifies several potential risks:
Regulatory Approval: Delays or rejection of required regulatory approvals may affect launch plans.
Licensing Dependency: The platform's initial operations may depend on a licensed financial partner.
KYC/AML Failures: Weak customer verification or anti-money laundering controls may create compliance problems.
Cybersecurity Attacks: Hacking and system vulnerabilities may affect platform security and operations.
Fraud and Chargebacks: Fraudulent transactions and payment disputes may result in financial losses.
Data Privacy Breaches: Unauthorized access to customer information may create legal and operational consequences.
Partner Bank Termination: Changes in partner relationships may disrupt financial services.
Liquidity Pressure: Financial obligations and transaction demands may create liquidity challenges.
Consumer Protection Claims: Customer complaints or disputes may lead to legal and regulatory exposure.
Sanctions Screening Failures: Inadequate screening may result in compliance violations.
Lending Restrictions: Regulations may restrict micro-loans, deposit-like products, or other proposed financial services.
Investors should review the full Risk Disclosure and understand that displayed or projected returns are not guaranteed.
Explore the Future of Connected Finance
Digital payments, international transfers, and neo-banking services can address important financial needs for individuals and businesses.
However, the success of a digital financial platform depends on its technology, regulatory approvals, financial partners, customer adoption, security, and ability to operate sustainably.
Before making an investment decision, review the project details, business plan, investment options, and risk disclosures.
Explore the Neo-Banking & Cross-Border Money Transfer Platform →
After reviewing the project information and applicable terms, you can create a WeInvesta account to explore the next steps.
Ready to Grow Your Wealth?
Put your capital behind real-world projects with real assets behind them.