
Digital Money Exchange & Neo-Banking Investment | Weinvesta
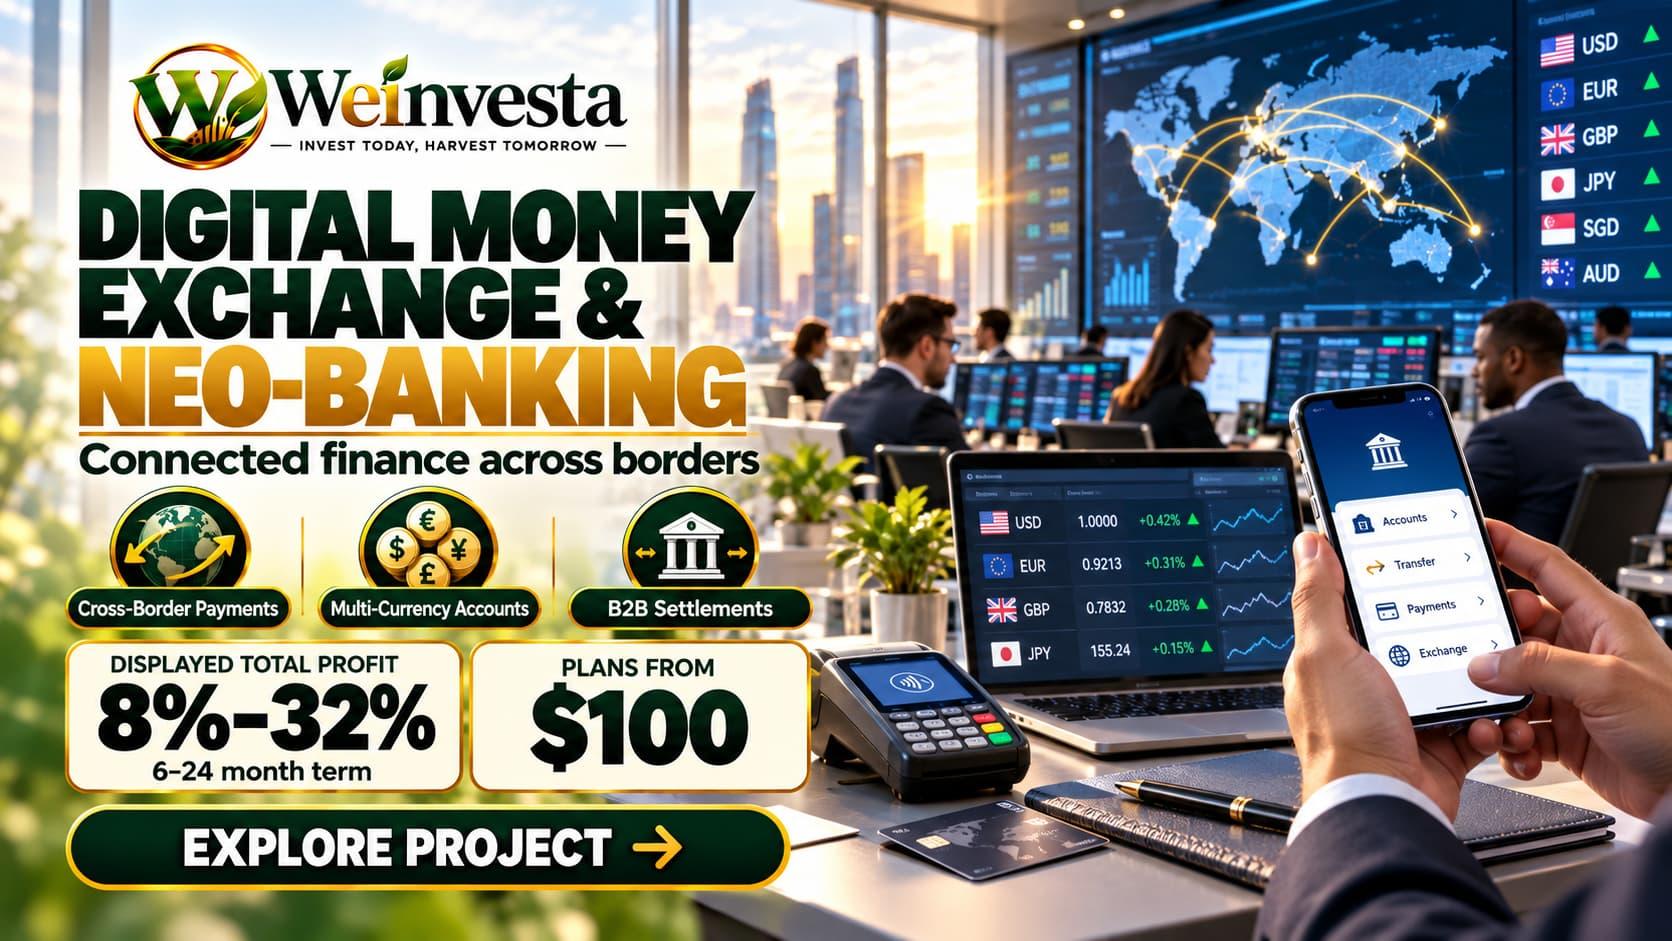
Digital Money Exchange & Neo-Banking: Building a Connected Financial Ecosystem
International commerce, remote work and e-commerce have increased demand for faster and more accessible cross-border financial services. Individuals and businesses increasingly expect to transfer money, exchange currencies, manage multiple accounts and complete payments through a connected digital platform.
Weinvesta’s Digital Money Exchange & Neo-Banking Project proposes a fintech ecosystem supporting cross-border remittances, digital currency exchange, merchant payments, multi-currency accounts and B2B trade settlements.
The planned markets include the United Kingdom, Lithuania, Latvia, Singapore and the United Arab Emirates.
Explore the Digital Money Exchange & Neo-Banking Project
Project overview
Category: Fintech & Payments
Status: Active
Target amount: $361,058.43
Raised so far: $0.00
Funding progress: 0%
Displayed total-profit range: 8%–32%
Available terms: 6, 12 or 24 months
Displayed investment range: $100–$1,000,000
Payout: At maturity
Maximum duration: 24 months
Funding progress, availability and terms may change. Review the live project page before making a decision.
What does the project plan to build?
The project proposes a digital financial platform designed to support:
Cross-border money transfers
Digital remittance services
Currency exchange
Multi-currency accounts
Merchant payments
Card-related services
B2B trade settlements
Transaction monitoring
Treasury-management services
Potential microfinance expansion
The objective is to connect these services within one digital ecosystem for consumers, merchants and international businesses.
Two-phase development plan
Phase 1: Banking-as-a-Service launch
The first phase plans to launch through a licensed Banking-as-a-Service partner.
The proposed infrastructure includes:
White-label core banking
Customer-account systems
Card issuing
Payment and remittance rails
KYC verification
AML monitoring
Transaction screening
Multi-currency capabilities
This approach may support a faster initial launch, but it also creates dependence on the licensed partner’s technology, permissions, pricing and service availability.
Phase 2: Licensing and expansion
After developing customer traction and compliance maturity, the project proposes pursuing direct banking or Electronic Money Institution licensing.
The second phase may introduce:
Direct payment infrastructure
Regulatory-capital development
Treasury management
Expanded currency services
Additional B2B financial tools
Microfinance services
Wider regional operations
Obtaining a banking or EMI licence remains subject to regulatory approval, governance standards, capital requirements and compliance readiness.
Potential revenue streams
Transaction fees
Small fees may be collected from remittances, merchant payments, business transfers and other completed transactions.
Foreign-exchange spreads
The platform may earn a margin from the difference between its currency-acquisition cost and the exchange rate offered to customers.
Merchant services
Businesses may pay processing, settlement or account-management fees.
Subscription services
Premium accounts, additional cards, advanced reporting and business tools may generate recurring revenue.
B2B settlements
International businesses may pay for multi-currency management, transaction reporting and faster cross-border settlements.
Displayed investment options
Six-month plan
Displayed total profit: 8%
Lock period: 6 months
Investment range: $100–$1,000,000
Payout: At maturity
Twelve-month plan
Displayed total profit: 16%
Lock period: 12 months
Investment range: $100–$1,000,000
Payout: At maturity
Twenty-four-month plan
Displayed total profit: 32%
Lock period: 24 months
Investment range: $100–$1,000,000
Payout: At maturity
View all related investment options
These figures describe the options displayed on the project page and do not guarantee future results.
Important information about the published terms
The project page currently presents two sets of information:
The live plan cards display investments from $100, with total-profit figures of 8%, 16% and 32%.
The longer project narrative mentions an earlier assumption of a $1,000 minimum, a 24-month lock, a 20% target return and a 20%–27% plan band.
Investors should review the live option selected during checkout, the applicable agreement and the latest project documents. Contact Weinvesta if any information appears inconsistent.
Principal risks
Regulatory and licensing risk
Payment, currency-exchange and banking services are heavily regulated. Licensing delays or restrictions could affect the project.
Banking-partner dependency
The first phase may depend on a Banking-as-a-Service provider. Changes to the partner’s permissions, prices or services could affect operations.
Cybersecurity and fraud
The platform may face hacking, account takeover, fraudulent transactions, data theft and chargeback risks.
KYC and AML compliance
Inadequate identity verification or transaction monitoring may lead to regulatory action, financial penalties or service restrictions.
Foreign-exchange and liquidity risk
Currency fluctuations and insufficient liquidity may affect transaction costs, settlement times and operating margins.
Technology risk
Software defects, cloud outages or third-party integration failures may interrupt access to financial services.
Customer-adoption risk
The project must attract enough users and merchants to create sustainable transaction volume.
Capital requirements
The estimated capital requirement across both phases is approximately $10.5 million–$14.5 million. Actual development costs may be higher.
Review the Risk Disclosure and Terms and Conditions before participating.
How to explore the project
Open the project page.
Review the business model, rollout plan and risks.
Compare the 6-, 12- and 24-month options.
Read the Weinvesta Whitepaper.
Compare the available investment plans.
Create an account and complete any required verification.
Use the investment button beneath the relevant option.
New users can read How Weinvesta Works.
Frequently asked questions
What services are planned?
Cross-border remittances, currency exchange, multi-currency accounts, merchant payments and B2B settlements.
Which countries are included?
The United Kingdom, Lithuania, Latvia, Singapore and the UAE.
What profits are displayed?
8% for 6 months, 16% for 12 months and 32% for 24 months.
When are payouts scheduled?
At maturity, according to the displayed plans.
Are returns guaranteed?
No. Results may be affected by regulation, licensing, transaction volume, cybersecurity, liquidity, foreign-exchange movements and other risks.
Explore connected digital finance
The project aims to connect international transfers, currency exchange, merchant payments and business settlements through a unified financial-technology ecosystem.
Ready to Grow Your Wealth?
Put your capital behind real-world projects with real assets behind them.